What is personal cyber insurance?
Personal cyber insurance, also called family or household cyber insurance, helps your household recover financially after an online attack, scam or data breach. It’s built for families, not businesses, and covers what actually happens at home: stolen money, hijacked accounts, locked devices, identity theft and online harassment.
Does homeowners insurance cover cyber attacks?
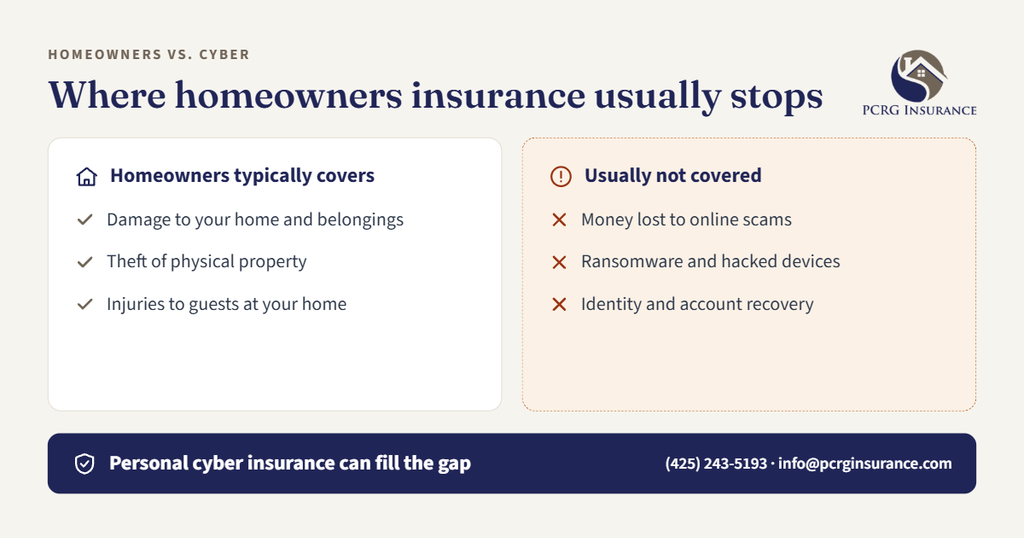
Usually not, or only for small amounts. Homeowners policies are designed for physical damage and theft of physical property. Some carriers offer cyber protection as an endorsement to a homeowners or high-value home policy; others offer a standalone policy with higher limits. We’ll check what you have and show you any gaps.
What does personal cyber insurance cover?
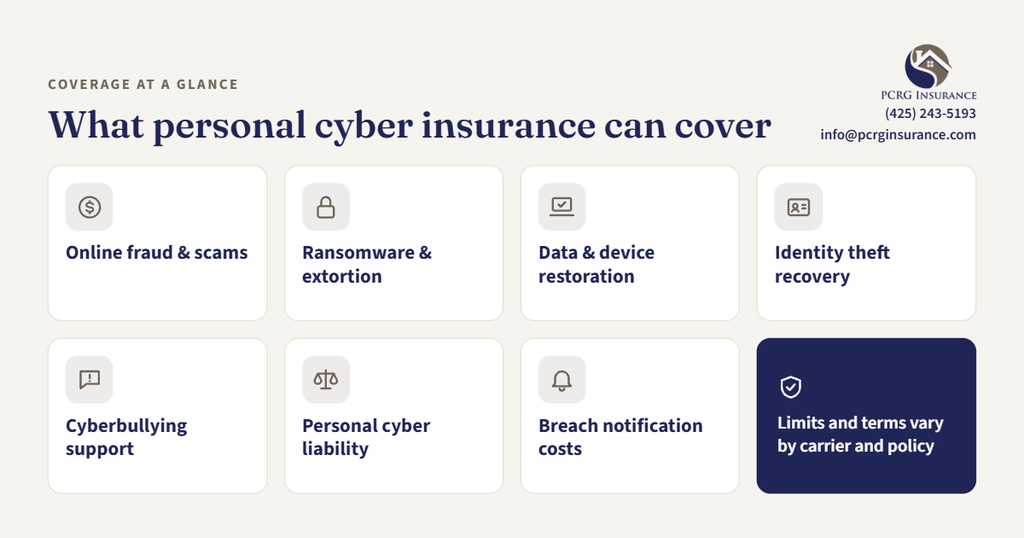
Coverage varies by carrier and policy, but personal cyber insurance often includes:
Online fraud and scams
Money lost to phishing, fake invoices, impersonation and fraudulent wire transfers
Cyber extortion and ransomware
Expert response to ransom demands and, where legal, the payment itself
Data and device restoration
Removing malware and restoring computers, phones and smart home devices
Identity theft recovery
Case management, lost wages and legal costs to restore your credit and accounts
Cyberbullying coverage
Counseling, tutoring, relocation or legal costs when a family member is targeted online
Personal cyber liability
Defense if your family is accused of spreading malware, privacy violations or online defamation
Breach breach costs
Notification and credit monitoring if data you hold, such as a household employee’s records, is exposed
Who needs personal cyber insurance?
Any family that banks, shops or works online has cyber risk. Coverage is especially worth reviewing if you:
- Have significant savings, investments or real estate, or regularly move large sums of money
- Are buying or selling a home (wire fraud around closings is common)
- Have children or teens active online, or aging parents who may be targeted by scams
- Work from home, use smart home devices, or employ household staff
- Have a public profile as an executive, physician, attorney or community leader
How much does personal cyber insurance cost?
Personal cyber insurance is one of the more affordable coverages a family can add. Price depends on your limits, deductible, household size and whether it’s an endorsement or standalone policy. We compare multiple carriers so you pay only for the protection you need.
Why families choose PCRG for personal cyber insurance
Independent carrier comparison
We compare personal cyber options from top-rated carriers instead of selling one company’s policy
Coordinated with your home, auto and umbrella coverage
We review cyber alongside your home, auto, umbrella and valuables coverage so nothing overlaps or falls through the cracks
Claims assistance when it happens
If you’re hit by a scam or attack, call us first and we’ll help you start the claim
Personal Cyber Insurance Guides for Families
Want to learn more before you talk to us? Download our family guide to preventing wire fraud, ID theft and online scams.
Personal cyber insurance FAQs: scams, limits and who’s covered
Does personal cyber insurance cover scams where I sent the money myself?
Many policies do, under online fraud or social engineering coverage, but limits and conditions vary. Some policies cover only hacks, not scams you were tricked into. We’ll confirm exactly how each option handles this before you buy.
Who is covered by personal cyber insurance in my household?
Most policies cover resident family members, typically including children living at home and often full-time students away at school. Some also extend to household employees. We’ll confirm who counts as a covered household member on each policy we quote.
Should I add cyber coverage to my homeowners policy or buy a standalone policy?
An endorsement to your homeowners policy is simple and affordable but usually has lower limits. A standalone policy typically offers higher limits and broader coverage, which suits families with significant assets or large online transactions. We’ll compare both for you.
How much personal cyber insurance do I need?
It depends on how much money you move online, your assets and your household’s online exposure. Families making large transactions, such as buying a home, often choose higher fraud limits. A PCRG advisor will help match limits to your real risk.
Does personal cyber insurance cover past cyber incidents?
Generally no. Like most insurance, personal cyber policies cover incidents that occur or are discovered after coverage begins. If you’ve just been scammed, report it at IdentityTheft.gov and call us so we can check your existing policies and help protect you going forward.
Get a free personal cyber insurance review
Most families don’t know whether they’re covered for a cyber loss until it’s too late. A PCRG advisor will review your current policies, show you any gaps, and compare personal cyber options. For a complimentary insurance review from one of our agents, feel free to submit a request through our online form below or give us a call at (425) 243-5193.